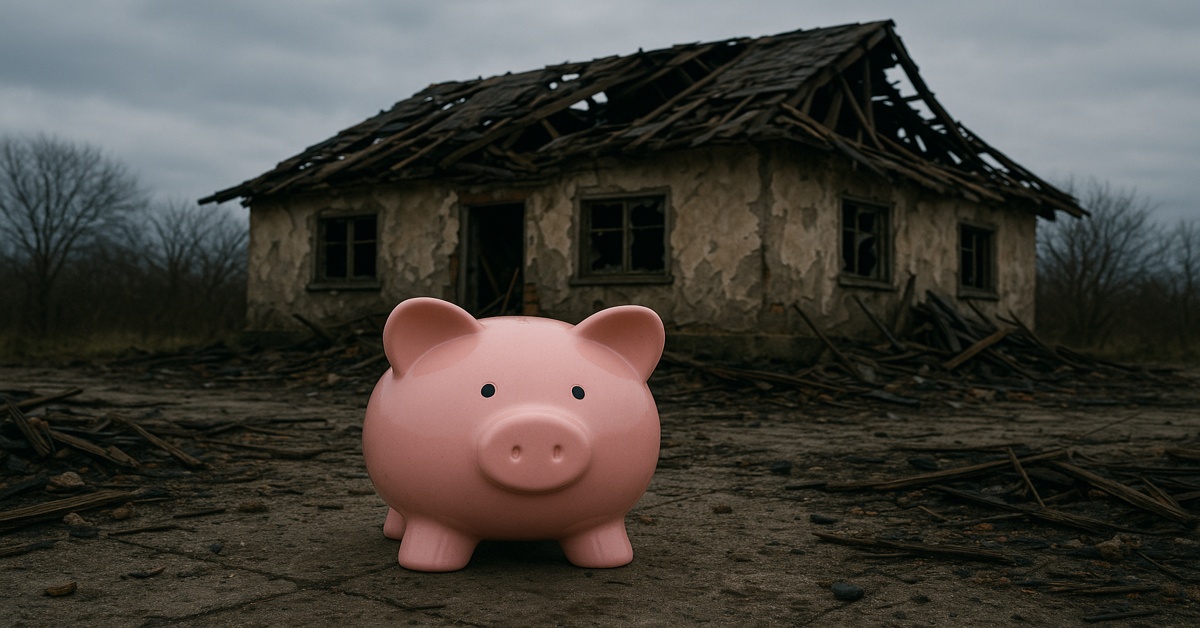
Penny-wise, but pound foolish – How reducing your premiums by insuring for less could cost your business in the long run
Underinsurance is a situation where the cover provided by an insurance policy is less than the actual value of the property and the income generated by a business.
It is an issue which frequently arises when dealing with insurance claims, and is often the consequence of a business either misunderstanding the need to insure its property for full replacement value or, worse still, because the business has declared a value for its property that is less than the full replacement value in an attempt to save money on insurance premiums.
Many policies contain provisions for “underinsurance” or “co-insurance” which deal with the consequences of inadequately declaring the value of business property, and they can have a significant impact on claim outcomes.
Assume, for example, that a business:
1. Declares the replacement value of a building to be $500,000, but the actual cost of replacing the building at the time is $1,000,000;
2. The building is damaged by fire; and
3. The cost of repairing the damage is $400,000.
In that scenario, the business will be underinsured, and the insurer would only be required to pay out an amount proportionate to the level of underinsurance. In the above example, the most the insurer could be required to pay is 50% of the total costs of repair.
That is to say, although the cost of repair is $400,000, and the policy is taken out for $500,000. The insurer will only be liable to pay out $200,000.
Obviously, this can have a significant impact on the business, which is now faced with the prospect of being unable to get back up and running if it is unable to finance the remainder of the cost to repair the property.
While most policies allow for some level of error in declaring the relevant value, it is often insufficient to protect against the consequence of underinsurance entirely.
Underinsurance is preventable and avoidable, and businesses should take caution of the risks associated with it.
There are a number of ways to prevent underinsurance.
1. Understand the actual policy requirements – The basis upon which you are required to insure may differ from policy to policy. Some require all property used in the business to be declared as a single value, including buildings, contents, and other property. Others require you to declare different types of property separately. Make sure you know the requirements of your policy and act accordingly.
Most business insurance policies also require you to declare the cost of replacing your property with new property. Don’t fall into the trap of declaring the cost of replacing with second-hand property.
2. Account for all of your property – Make a list of each and every item which might be covered by the policy.
3. Don’t settle for a lower premium – Don’t try and save money on your insurance premiums by taking out insufficient cover. Try to insure for the correct value of assets.
4. Don’t guess – Take the time to research the cost of repair and replacement. Take advantage of online building calculator such as the one made available by the Insurance Council of Australia. Seek the assistance of a professional valuation company.
5. Don’t set and forget – Review your value of your property and the income you generate frequently. Values change over time. Costs of rebuilding increase. Businesses should frequently assess their level of cover, and ensure that it remains adequate.
About the Author
LMI Legal is a law firm offering advice, and litigation and dispute resolution services to all involved in the insurance industry, including insureds and insurance brokers, Australia-wide. We focus on insurance law because that is what we know, and what we know best.
Since its inception, LMI Legal has grown to become the well respected and formidable insurance litigation firm that it is today, having acted on behalf of insureds in every state and territory, and across all state and federal jurisdictions, including the High Court of Australia.
LMI Legal welcomes any queries you may have relating to an insurance coverage issue.
Telephone: 02 8404 0550
Email: info@lmilegal.com
Website: https://lmilegal.com/
LinkedIn: https://www.linkedin.com/company/lmi-legal/
Disclaimer
The information contained in this article is provided as general advice only. The contents of it have been prepared without taking account of your particular circumstances or objectives. You should consult with your own insurance advisor before making any decision relating to your insurance needs.